

Lithuanian IBAN accounts for non-residents
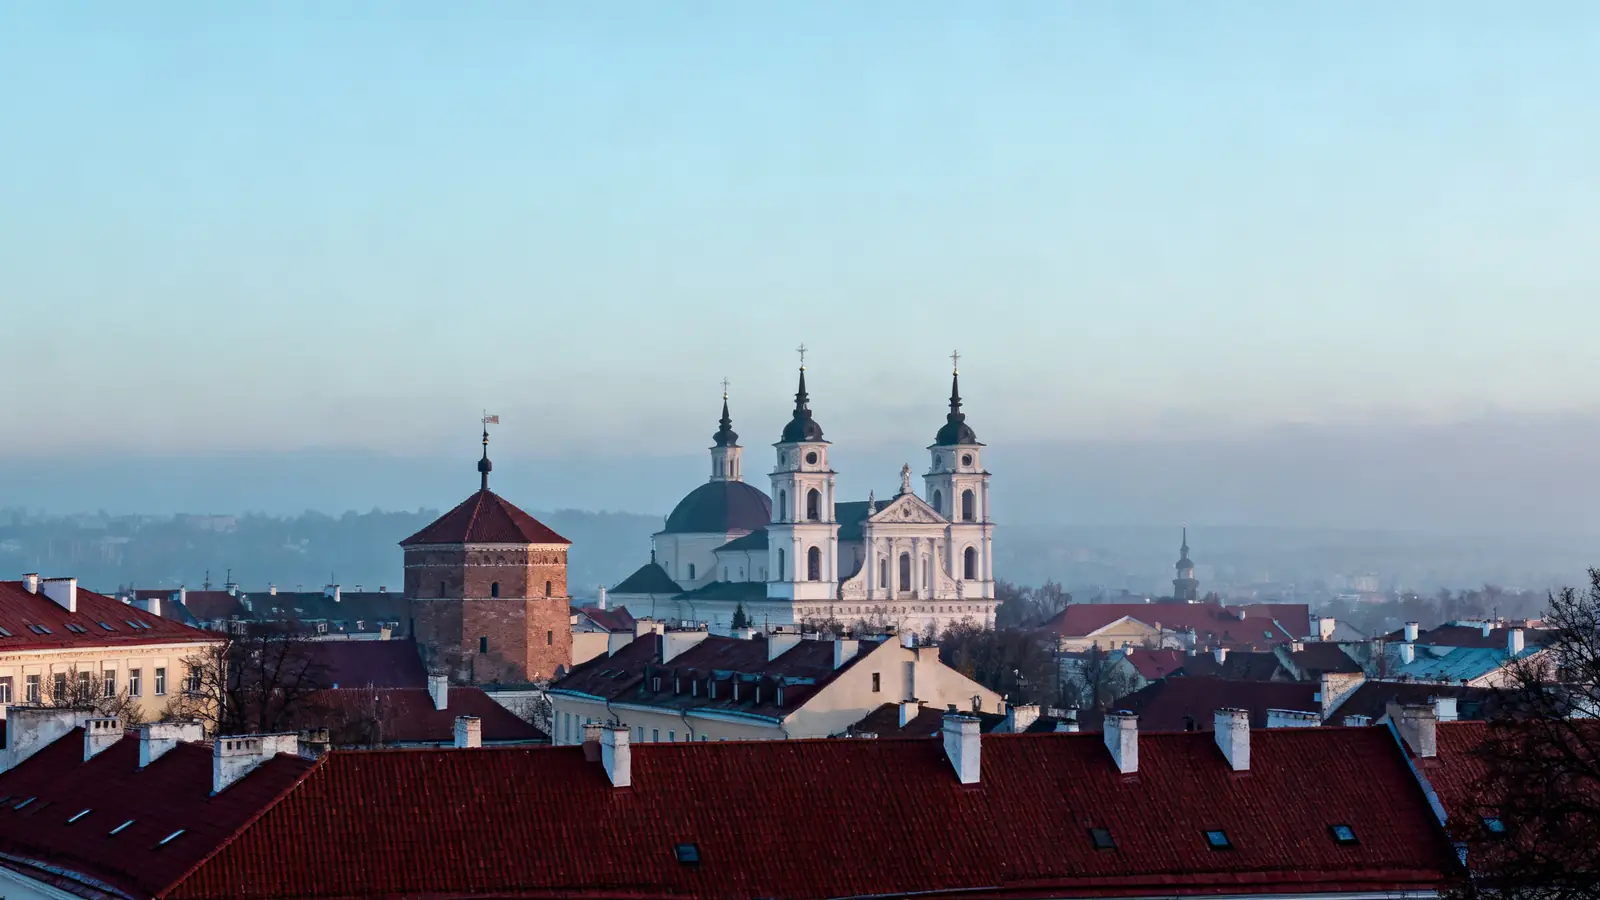
 LithuaniaEurope
- EMI safeguarding methods
- Segregated account at a credit institution, secure low-risk assets, or cover by an insurance policy or comparable undertaking
- As of 2026-10-25 · [2]
Overview
Lithuania has become one of the EU's main licensing hubs for electronic money and payment institutions. For international founders the attraction is practical: an account with a Lithuanian IBAN in your own or your company's name, euro payments through SEPA and, depending on the provider, balances in several currencies and payment cards, usually opened without travelling.
What is the difference between an EMI and a bank?
A bank takes deposits and lends them out. Its deposits are insured up to EUR 100,000 per depositor and bank, in any currency, with payout due within seven working days. An EMI may not lend client money; it must safeguard it, usually in a segregated account at a bank or in secure, liquid low-risk assets, so that the EMI's own creditors cannot claim it. Electronic money is expressly excluded from deposit insurance.
Safeguarding is real protection, but it is not insurance. If an EMI fails, client money is returned through an insolvency process rather than an insurance payout, which takes longer. And because deposits held by financial institutions are excluded from deposit insurance, the EMI's own safeguarding account at a bank is not insured either.
How Lithuanian EMIs reach SEPA
The Bank of Lithuania operates CENTROlink, a payment system that gives licensed EMIs and payment institutions access to SEPA credit transfers, SEPA instant transfers and SEPA direct debits. Under Article 9 of the SEPA Regulation, payers and payees in the EU may not insist that an account be held in a particular member state, so an LT IBAN should be accepted for euro payments across the EU. Refusals still happen and can be reported to the competent national authority.
Lithuania bank account for non-residents: requirements
- Identity verification for every holder, director and beneficial owner, usually a passport scan plus a video or selfie check.
- Proof of residential address and a tax residency self-certification with your tax number.
- For companies: formation documents, a registry extract, a shareholder register and an ownership chart down to the individuals.
- A description of the business: what you sell, where customers and suppliers are based, expected monthly volumes and currencies.
- Source of funds for the first payments, and later invoices or contracts when larger transfers arrive.
Providers set their own country lists and sector policies. Some accept non-EU residents and non-EU companies; others serve EU residents only.
Open a bank account in Lithuania online
Most EMIs onboard entirely online. Traditional Lithuanian banks are more selective with non-residents and often expect a local connection, which is why our Lithuanian network is built on EMIs. Before applying, check the provider in the Bank of Lithuania's public register of market participants and confirm which licensed entity will hold your money.
E-residency is not a bank account
Lithuania grants an e-resident status, administered by the Migration Department, that provides a digital identity for remote public and commercial e-services. It can simplify paperwork, but it does not oblige any bank or EMI to open an account. The same is true of Estonia's e-Residency: each provider still runs its own checks.
- CENTROlink schemes
- SEPA credit transfers, instant credit transfers, direct debitsAs of 2026-10-25 · [3]
- SEPA Regulation, Article 9
- Payers and payees may not dictate the EU member state of the accountAs of 2026-10-25 · [4]
- First CRS exchanges
- 2017As of 2026-09-30 · [7]
- FATCA
- Model 1 agreement in force since 2014-10-07As of 2026-10-25 · [8]
Banking in our network
We do not publish institution names: the right partner depends on your profile, and each institution keeps its own view on who it will serve.
7
Banking partners
- Our Lithuanian network is made up of EMIs and multi-currency providers rather than traditional banks. Each provider runs its own onboarding and may decline without giving reasons.
- EMIs suit operating and backup accounts: receiving client payments, paying suppliers and running cards. For holding larger reserves, a bank account with deposit insurance or a separate treasury relationship is usually the better fit.
- Risk appetite differs sharply between providers on nationality, residence and sector. We check where your profile fits before you apply.
- If customers need to pay you directly, confirm the account comes with a dedicated IBAN in your own or your company's name rather than a pooled account.
Questions
Can a non-resident open a bank account in Lithuania?
Yes. Lithuanian EMIs open accounts for many non-residents and non-EU companies, usually fully online. Traditional banks are more selective and often want a local link. Every provider applies its own due diligence and country list, so approval is never guaranteed.
What is the difference between an EMI and a bank?
A bank lends out deposits, and its depositors are insured up to EUR 100,000. An EMI cannot lend client money; it must safeguard it, typically in a segregated bank account, so that the EMI's creditors cannot reach it. Electronic money is not covered by deposit insurance.
Is my money safe with a Lithuanian EMI?
It is protected differently. Safeguarding ring-fences client money from the EMI's own creditors, but there is no insurance payout, and recovery after a failure can take time. If the bank holding the safeguarded funds fails, that deposit is not insured either. Spread larger balances accordingly.
Will a Lithuanian IBAN be accepted in other EU countries?
It should be. The SEPA Regulation bars payers and payees in the EU from requiring an account in a particular member state, as long as the account is reachable through SEPA. If an employer, utility or merchant refuses an LT IBAN, you can report it to the national competent authority.
Can I open a Lithuanian account online?
Usually yes with an EMI: identification by document scan and a video or selfie check, followed by questions about your activity and the source of funds. Expect follow-up requests for invoices, contracts or bank statements, especially for companies with international counterparties.
Does Lithuanian e-residency give me a bank account?
No. E-resident status gives you a digital identity for remote public and commercial services. It can make paperwork easier, but banks and EMIs still decide independently after their own checks. The same applies to Estonia's e-Residency.
Is a Lithuanian account reported to my tax authority?
Expect so. Lithuania has exchanged financial account information under the CRS since 2017 and reports US persons under a FATCA agreement. Providers ask for your tax residency and tax number at onboarding and report the accounts that fall within these rules.
Sources
- 1.Deposit and Investment Insurance (Indėlių ir investicijų draudimas): FAQ on deposit insurance, retrieved 2026-10-25
- 2.Bank of Lithuania: What client fund safeguarding requirements apply to payment or e-money institutions?, retrieved 2026-10-25
- 3.Bank of Lithuania: CENTROlink payment system, retrieved 2026-10-25
- 4.EUR-Lex: Regulation (EU) No 260/2012 (SEPA Regulation), Article 9 on accessibility of payments, retrieved 2026-10-25
- 5.Migration Department under the Ministry of the Interior: E-resident, retrieved 2026-10-25
- 6.Bank of Lithuania: Register of financial market participants, retrieved 2026-10-25
- 7.OECD Global Forum: Status of commitments for the automatic exchange of financial account information (30 September 2026), retrieved 2026-10-25
- 8.US Treasury: FATCA agreements and understandings by jurisdiction, retrieved 2026-10-25
- 9.Redomiciled banking classroom, chapter 3: which bank is best for me (internal), retrieved 2026-10-25
Reviewed by the Redomiciled team on .
Plan your next step in Lithuania.
Answer a few questions and we come back with a recommendation for your situation, without obligation.