

Swiss bank accounts for non-residents
 SwitzerlandEurope
- Supervisor
- FINMA (Swiss Financial Market Supervisory Authority)
- Funding the banks commit to deposit protection
- Up to CHF 8.1 billion (1.6% of protected deposits)
- As of 2026-10-25 · [1]
Overview
Switzerland is still one of the deepest pools of cross-border private banking. At the end of 2025, banks in Switzerland managed CHF 9,729.1 billion in assets, and 45.9% of that belonged to clients domiciled abroad. What has changed is the basis of the relationship: Swiss banks now compete on stability, service and investment capability, not on hiding money.
What a Swiss account is good for
Swiss banks are strongest at holding and managing wealth: accounts in several currencies, custody of securities and a named relationship manager. Securities in a custody account remain the client's property and are kept apart from the bank's own assets, while cash balances are deposits and fall under deposit protection. In the three-account model we use, a Swiss bank usually takes the treasury role, holding accumulated capital, rather than processing high-volume daily payments.
Is Swiss banking secrecy still a thing in 2026?
Swiss law still makes it a criminal offence for bank staff to disclose client information without a legal basis (Article 47 of the Banking Act). That is client confidentiality towards third parties, not secrecy towards tax authorities. The legal basis for the automatic exchange of information has been in force since 1 January 2017, and Swiss banks report accounts of clients resident in partner states to the Federal Tax Administration, which forwards the data. US persons are reported under FATCA. Treat a Swiss account as fully visible to your home tax authority.
Swiss bank account for non-residents: requirements
Swiss banks follow the due-diligence code CDB 20, which governs how they identify the contracting partner, controlling persons and beneficial owners. Expect to provide:
- A valid passport and recent proof of residential address for every holder, signatory and beneficial owner.
- A tax residency self-certification with your tax identification number, plus a declaration of whether you are a US person.
- Evidence of source of wealth: how the assets were built over time, for example sale agreements, dividend statements or employment records.
- The source of the first transfer and a short description of expected activity: amounts, currencies, counterparties.
- For companies: a registry extract, articles, an ownership chart down to the individuals and a plain description of the business.
Swiss bank account online for non-residents
FINMA Circular 2016/7 lets banks identify clients by video or online instead of in person. A revised version, adding the Swiss e-ID and liveness detection, enters into force on 1 November 2026. Whether a bank offers remote onboarding to non-residents is its own decision: many private banks still prefer a meeting, and app-based providers often accept only certain countries of residence.
Banks versus FinTech-licensed firms
Not every Swiss-licensed provider is a bank. A firm with a FinTech licence may accept up to CHF 100 million in public deposits, but it may not invest them or pay interest, and if it fails those balances are neither privileged nor covered by deposit protection. Check the licence type before you move money.
Redomiciled prepares the application file and introduces you to banks whose risk appetite fits your profile. The bank alone decides, and an account is never guaranteed.
- FATCA
- Model 2 agreement in force since 2014-06-02; Model 1 agreement signed 2024-06-27, not yet appliedAs of 2026-10-25 · [6]
- Assets under management at banks in Switzerland
- CHF 9,729.1 billion45.9% held for clients domiciled abroadAs of 2025-12-31 · [7]
- Due-diligence code for banks
- CDB 20, in force since 2020-01-01As of 2026-10-25 · [8]
- Video and online identification
- Permitted under FINMA Circular 2016/7; revised version in force from 2026-11-01As of 2026-10-08 · [3]
- FinTech licence: deposit ceiling
- CHF 100 million, without deposit protectionAs of 2026-10-25 · [2]
Banking in our network
We do not publish institution names: the right partner depends on your profile, and each institution keeps its own view on who it will serve.
8
Banking partners
- Our Swiss network covers private banks, corporate banking and crypto-aware institutions. Each application is decided by the bank after its own due diligence.
- Private banks expect a meaningful relationship size and a coherent source-of-wealth story. Thresholds differ widely between banks and are confirmed during onboarding rather than published.
- Company accounts work best for businesses with real activity and a clear reason to bank in Switzerland. Holding companies without operations draw more questions.
- Some banks decline or limit clients who are US persons because of FATCA reporting. Mention US citizenship, green cards or US tax filings at the start.
- Crypto-derived wealth is bankable at some Swiss institutions if the trail from purchase to sale is documented.
Questions
Can a non-resident open a Swiss bank account?
Yes. Swiss law does not require residence, and banks open personal and company accounts for non-residents. Each bank decides after checking identity, source of wealth and tax status, so approval is never guaranteed. Some banks restrict certain countries of residence or US persons.
Is Swiss banking secrecy still a thing in 2026?
Client confidentiality is: disclosing client data without a legal basis is a crime under Article 47 of the Banking Act. Tax secrecy is not. Switzerland exchanges account data automatically with its CRS partner states and reports US persons under FATCA, so your home tax authority can see the account.
What documents do Swiss banks ask for?
A passport, proof of address, tax residency and tax number for each holder and beneficial owner, plus evidence of source of wealth and of the first funds. Companies add a registry extract, articles, an ownership chart down to the individuals and a description of the business.
Can I open a Swiss bank account online?
Sometimes. FINMA allows video and online identification, and a revised circular adds the Swiss e-ID from 1 November 2026. Whether a bank onboards non-residents remotely is its own choice; private banks often still want a meeting in Switzerland or with a banker abroad.
How much money do I need for a Swiss bank account?
There is no legal minimum. Private banks set their own relationship sizes, which vary widely and are discussed during onboarding. App-based and retail providers usually ask for far less but serve fewer countries of residence. Clarify the expected size before applying.
Are deposits in a Swiss bank protected?
Cash deposits at a licensed bank are protected up to CHF 100,000 per client and bank through esisuisse. Securities in custody are not deposits; they remain the client's property and are kept separate from the bank's assets. Balances at FinTech-licensed firms are not covered.
What is the best Swiss bank account for non-residents?
There is no single best bank. The right one depends on the job the account has to do, your country of residence, the currencies you need, the size of the relationship and whether crypto or US links are involved. We match those criteria to banks that accept your profile.
Videos
Which Small Country Has the Best Banking Hub?
Georgia, Mauritius, Panama, Uruguay, Switzerland or Liechtenstein? We compare smaller banking hubs for diversification, private banking, international clients and high-touch service — and see how they stack up against each other.
Fastest Bank Accounts by Country (Tier List)
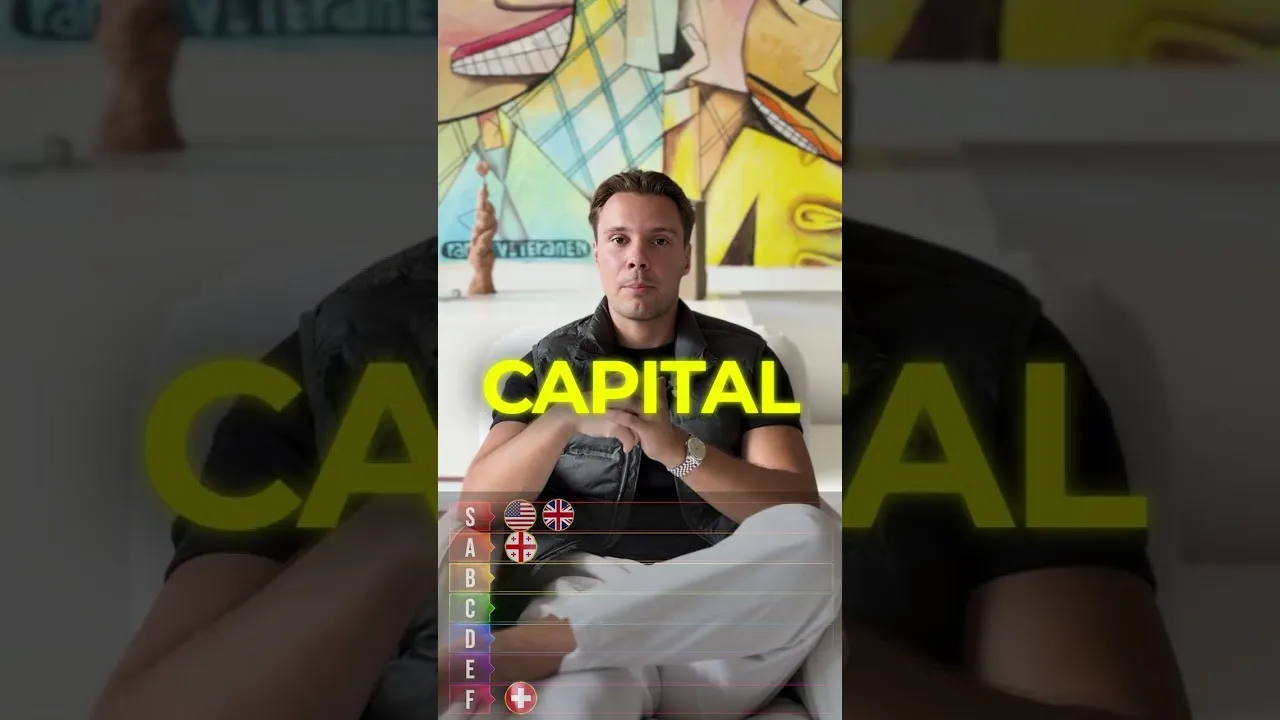
A tier list of how fast a bank account can be opened in Georgia, the USA, Switzerland, the UK, Panama and the UAE, and why the quickest account is not always the right one.
I Ranked The World’s Best Banking Jurisdictions (After 650+ Accounts)
After opening more than 650 bank accounts across 48 jurisdictions, one lesson stands out: the best banking jurisdiction depends on your profile, risk class and operating needs. This video compares major banking hubs and explains what actually determines fit.
Sources
- 1.esisuisse: The Swiss deposit insurance system, retrieved 2026-10-25
- 2.FINMA: FinTech licence, retrieved 2026-10-25
- 3.FINMA: FINMA adopts partially revised Circular 2016/7 "Video and online identification" (8 October 2026), retrieved 2026-10-25
- 4.State Secretariat for International Finance (SIF): Automatic exchange of information on financial accounts, retrieved 2026-10-25
- 5.Federal Council: Switzerland and United States agree on mutual exchange of financial account data (27 June 2024), retrieved 2026-10-25
- 6.US Treasury: FATCA agreements and understandings by jurisdiction, retrieved 2026-10-25
- 7.Swiss Bankers Association: Banking Barometer 2026, wealth management, retrieved 2026-10-25
- 8.Swiss Bankers Association: CDB 20, revised code of conduct in the fight against money laundering, retrieved 2026-10-25
- 9.Fedlex: Federal Act on Banks and Savings Banks (Banking Act, SR 952.0), retrieved 2026-10-25
- 10.OECD Global Forum: Status of commitments for the automatic exchange of financial account information (30 September 2026), retrieved 2026-10-25
- 11.Redomiciled banking classroom, chapter 3: which bank is best for me (internal), retrieved 2026-10-25
- 12.Redomiciled banking classroom, chapter 3: how to open a bank account and keep it open (internal), retrieved 2026-10-25
Reviewed by the Redomiciled team on .
Plan your next step in Switzerland.
Answer a few questions and we come back with a recommendation for your situation, without obligation.